
As the Business Changes, the Risk Changes
Businesses rarely stay exactly as they were when an insurance policy was first arranged. They grow, add equipment, take on new clients, hire staff, move premises, introduce new services and adopt new technology.
Each of these changes can alter the risks the business carries. The policy may still be active, but the information on which it was originally based may no longer reflect the operation as it exists today.
Reviewing insurance after a meaningful business change is therefore not about automatically buying more cover. It is about checking whether the existing protection still matches the assets, responsibilities and exposures the business now has.
New Assets Can Change the Value at Risk
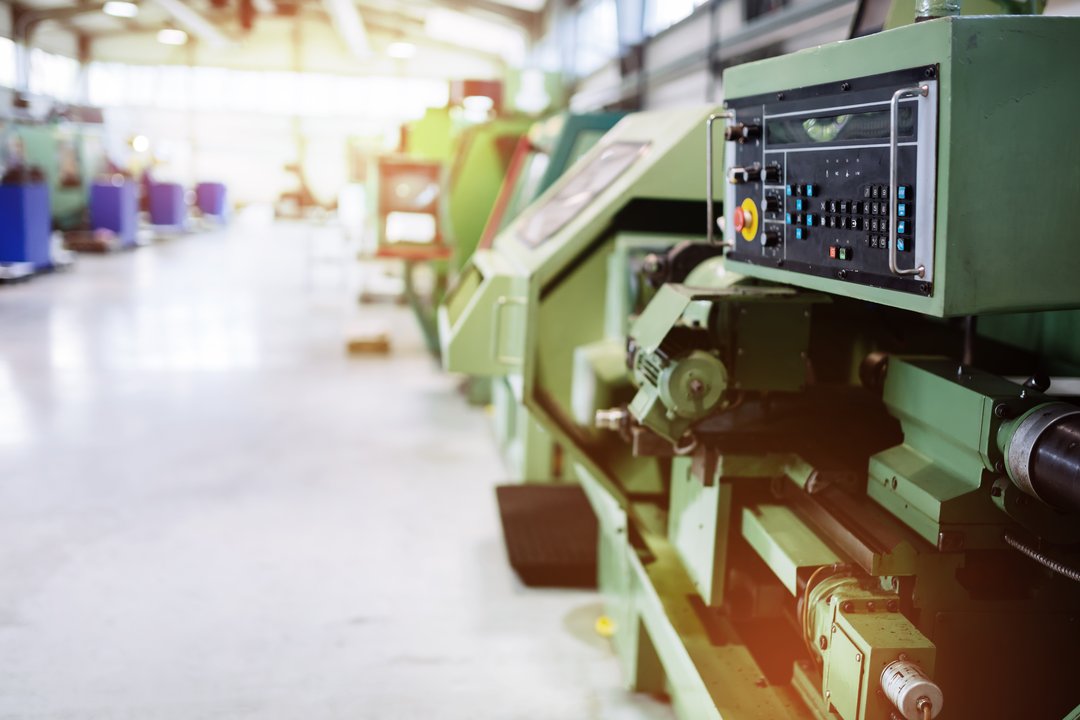
Growth often brings additional physical assets. A business may purchase machinery, expand its fleet, add specialist equipment or move into larger premises. It may also hold more stock than it did when its insurance was originally arranged.
These changes can affect both the type and value of the assets that need protection. If declared values are outdated, new equipment has not been considered or assets are being used at a different location, the insurance arrangement may no longer reflect the actual exposure.
Sinergi Risk provides Business Asset Insurance for vehicles, buildings, equipment and machinery. Keeping this information current gives the business and its broker a clearer basis for assessing what needs to be insured.
New Responsibilities Can Create Different Liabilities
A business can change significantly without buying a single new asset. Offering a new professional service, employing more people, selling different products or taking on additional contractual responsibilities can create different forms of liability.
A business that gives professional advice does not face exactly the same exposure as one manufacturing or supplying products. Employers have responsibilities to their staff, directors and officers can face claims connected to management decisions, and greater dependence on data and digital systems can introduce cyber liability.
Sinergi Risk’s liability offering includes General Liability, Professional Indemnity, Directors and Officers Liability, Employers Liability, Product Liability and Cyber Liability. The relevant cover depends on the activities and responsibilities of the individual business.
Contracts can also change the picture. New clients, suppliers or commercial partners may introduce different obligations, limits of liability or insurance requirements. When the terms under which a business operates change, it is worth checking that the insurance arrangements have kept pace with those responsibilities.
Operational Changes Matter Too
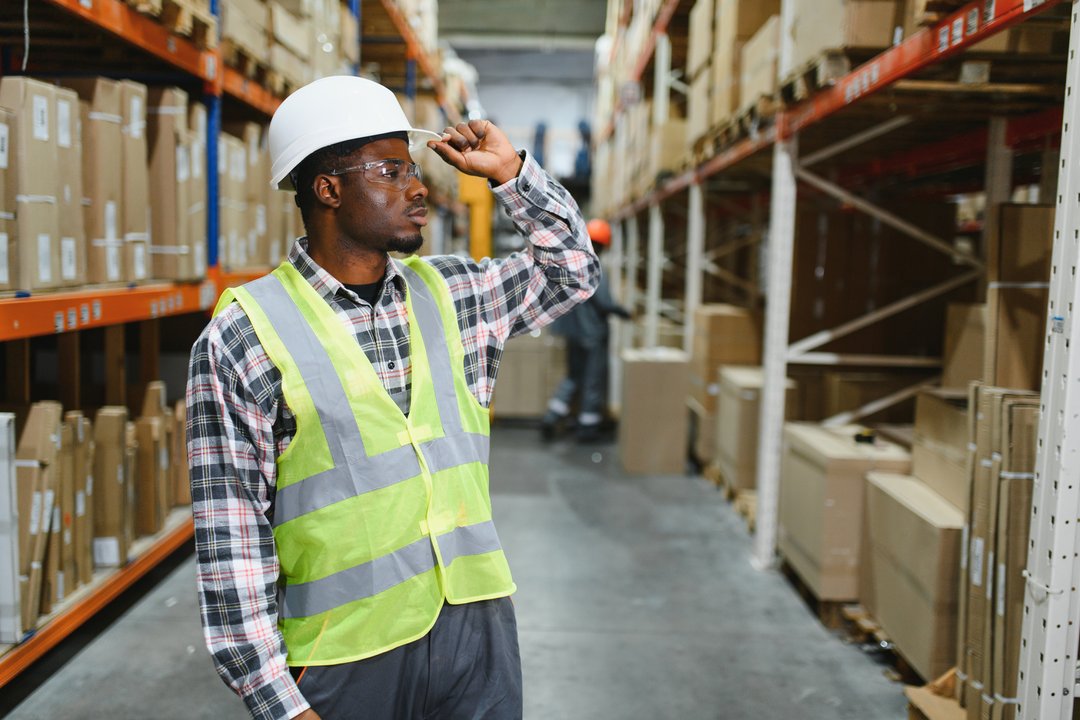
Changes to day-to-day operations can be just as important. A logistics business may begin using new routes, carry different goods, add vehicles, change storage arrangements or work with new transport partners. Another business may expand online, store more customer information or rely more heavily on digital systems.
None of these changes automatically means a new policy is required. They do, however, give the business a reason to check whether the existing insurance still reflects the way it now operates.
This is especially important where several policies work together. Cargo, Goods in Transit, Stock Throughput, Heavy Commercial Vehicle, Business Asset and Liability Insurance each address different exposures. A change in one part of the operation may affect more than one area of cover.
Insurance Should Reflect the Business You Run Today
Insurance gaps are often easiest to identify after a claim, when it is too late to correct outdated information or clarify what was intended to be covered.
A more practical approach is to review insurance when meaningful changes happen. New premises, higher asset values, additional services, different contracts, more employees or increased reliance on technology are all useful triggers for that conversation.
A review should also confirm that existing policy information remains accurate. Assets may have been sold, locations changed or activities discontinued, and those changes matter too.
The purpose is simple: to make sure the insurance programme reflects the business as it operates now, not the business it used to be.
Sinergi Risk provides tailored insurance solutions across logistics, business assets and liability, helping clients align their cover with their current risks and requirements.
If your business has changed, speak to Sinergi Risk about whether your insurance still fits.